Energy Tax Credits
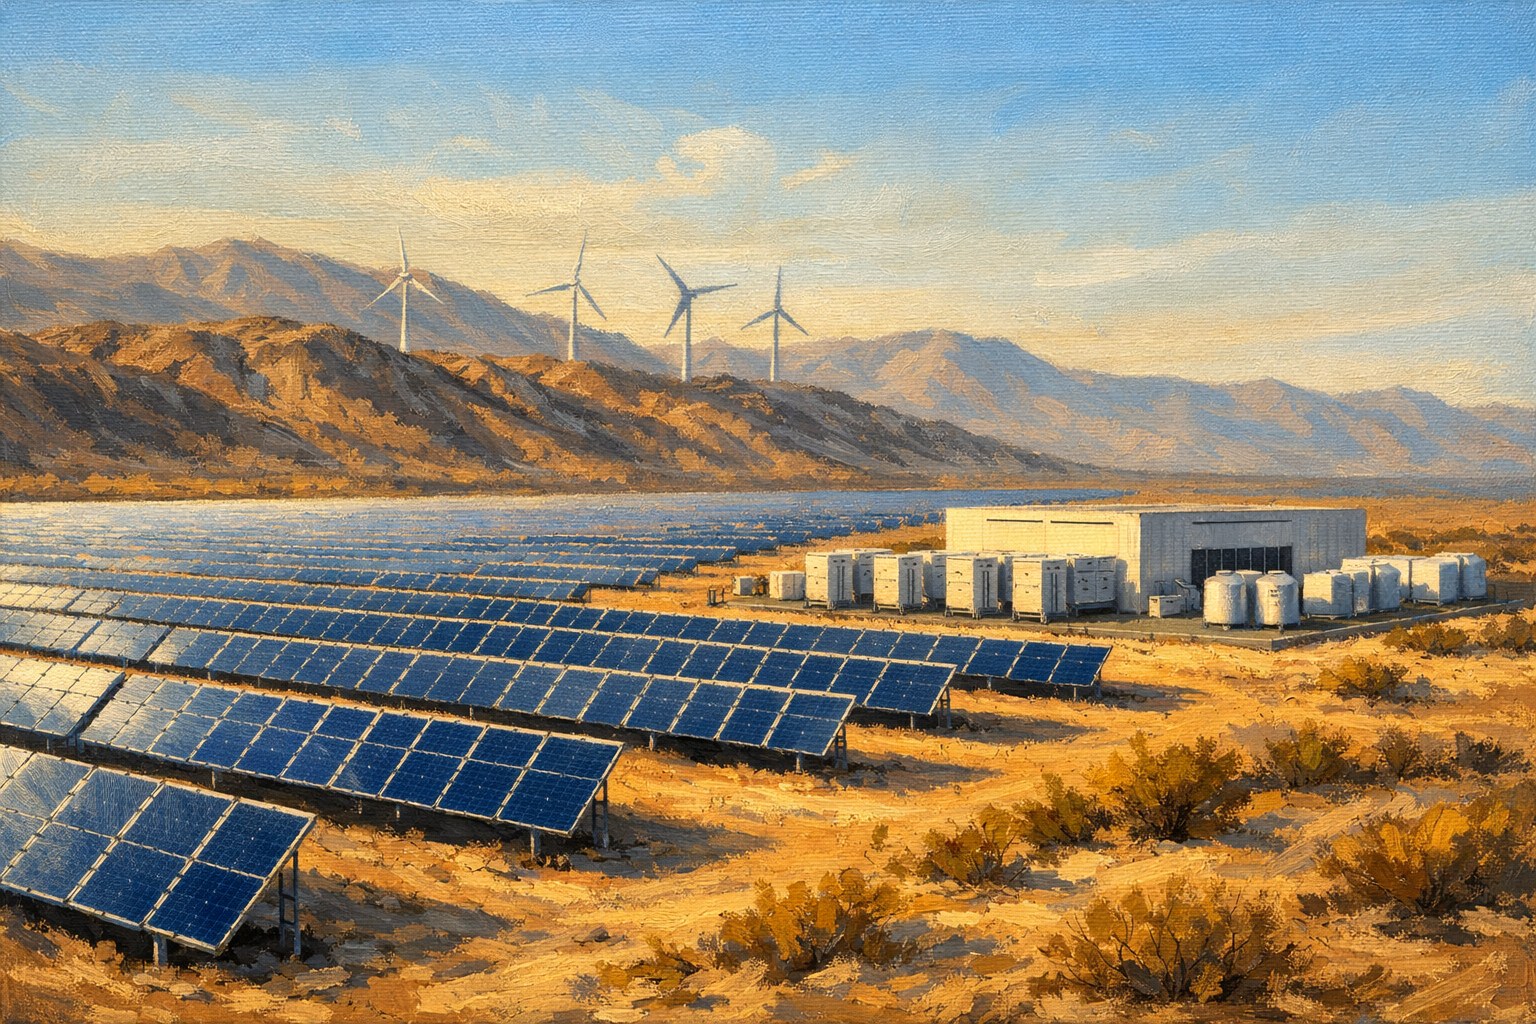
The tax code has long been a main tool of energy policy. Oil and gas producers have benefited from deductions for drilling costs and depletion since the early 20th century, and Congress created a production tax credit for wind in 1992 and an investment tax credit for solar in 2005, renewing them repeatedly. These credits helped wind and solar grow from tiny shares to about 17 percent of U.S. electricity combined by 2025.
The Inflation Reduction Act, signed August 16, 2022, passed with only Democratic votes, made the largest climate investment in U.S. history, extending and expanding credits for clean electricity, battery storage, nuclear plants, clean hydrogen, carbon capture, electric vehicles, home efficiency and solar, and domestic manufacturing of clean energy equipment. Estimates of its cost rose from about 270 billion dollars to far more as companies claimed the uncapped credits, and much of the new factory investment went to Republican-led states.
The 2025 budget law ended consumer electric vehicle credits after September 30, 2025, ended home efficiency and rooftop solar credits after 2025, and set wind and solar projects to lose credits unless they begin construction by July 2026 or are placed in service by the end of 2027, while keeping credits for nuclear, geothermal, storage, and carbon capture. Supporters of the cuts said the credits were costly subsidies for industries that should compete on their own. Opponents said ending them would raise electricity prices, cost manufacturing jobs, and slow the response to climate change.
| Status | Active |
| Legal basis | 26 U.S.C. 45, 48, and related sections |
| Official site | irs.gov |
| Wind credit | Created 1992 |
| Solar credit | Created 2005 |
| Inflation Reduction Act | Signed August 16, 2022 |
| EV credits ended | September 30, 2025 |
| Wind and solar | Credits phase out for projects after 2027 |
| Date | Inflation Reduction Act signed August 16, 2022 |